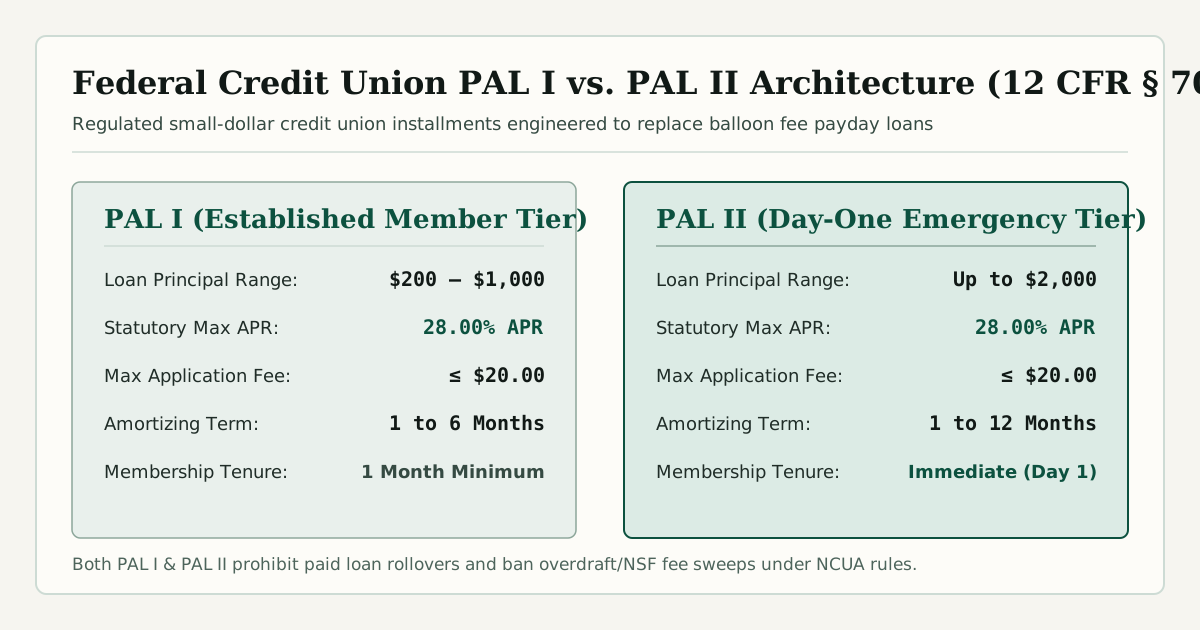
NCUA PAL I vs. PAL II Statutory Parameter Matrix (12 CFR § 701.21)
Federal credit unions chartered under the Federal Credit Union Act offer two regulated small-dollar loan tiers specifically engineered to replace single-payment balloon payday advances with amortizing principal-and-interest installments.
| Loan Attribute | NCUA PAL I | NCUA PAL II | Uncapped Payday Advance |
|---|---|---|---|
| Principal Range | $200 – $1,000 | Up to $2,000 | $100 – $1,000 |
| Maximum Interest Ceiling | 28.00% APR | 28.00% APR | 300% – 660% APR |
| Application Fee Limit | ≤ $20 actual cost | ≤ $20 actual cost | $15–$30 per $100 |
| Repayment Term | 1 to 6 months (amortizing) | 1 to 12 months (amortizing) | 7 to 31 days (lump sum) |
| Membership Tenure | At least 1 month | Immediate (Day 1 eligible) | Checking account + paystub |
| Paid Rollovers Allowed | Prohibited | Prohibited | Permitted in uncapped states |
How the Annualized Fee Formula Works
To translate any short-term flat dollar fee into a Truth-in-Lending Annual Percentage Rate, divide the total finance charge by the net cash proceeds you actually receive, multiply by 365 divided by the exact number of days until repayment, and express the result as a percentage:
APR = (Finance Charge ÷ Net Amount Financed) × (365 ÷ Term in Days) × 100For example, borrowing $400 for 14 days with a $60 finance fee produces (60 ÷ 400) × (365 ÷ 14) × 100 = 391.07% APR. Watch carefully for California-style face-value check deductions: if a lender writes a $300 check, deducts a $45 fee upfront, and hands you $255 in cash, your true finance ratio is 45 ÷ 255 (460.08% APR over 14 days), not 15%.